
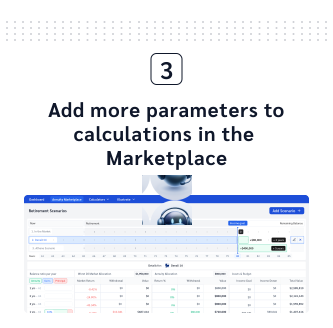
It seems that basic information is not enough to calculate your personal case
We need to consider more details to provide you with only 100% verified results.
With a decade of experience navigating the complex realities of retirement, I’ve seen far too many retirees believe a volatile market portfolio is the only way to generate income. My passion is challenging the '4% rule' with fixed strategies that protect your principal while providing the competitive, predictable yields you need for a confident retirement. My mission is simple: provide more predictable income, ensure zero market losses, and deliver the peace of mind that comes from knowing your guarantees are backed by the claims-paying ability of the strongest A++ rated institutions in America.
”Thank you!
You may leave your information for me to review before our call. That way, we can focus more on your needs and less on technical details.
Prepare for the callWhat is an annuity?
What type of annuity is right for you?
The type of annuity that's right for you will depend on your personal goals, objectives, and risk tolerance.
Multi-Year Guaranteed Annuities
A multi-year guaranteed annuity, or MYGA, offers a predetermined and contractually guaranteed interest rate for a fixed period of time.
-
Less market risk exposure
Since a MYGA offers a guaranteed interest rate for the entire contracted term, it may appeal to those who prefer predictability over market fluctuations. All guarantees are backed by the issuing insurance company’s claims-paying ability.
-
Flexibility and liquidity
The ability to take partial withdrawals each year without a penalty provides flexibility. For example, if you need money to cover a large medical bill, you could withdraw it from your MYGA, which might be a better option than taking money from an IRA or getting a 401(k) loan.


Traditional Fixed Annuities
Fixed annuities are insurance contracts that pay a guaranteed rate of interest on the account owner's contributions.
-
Predictable credited interest rates
The rates on fixed annuities are derived from the insurer’s general account, which is typically composed of high-quality bonds and other conservative holdings.
-
Guaranteed minimum rates
Once the initial guarantee period in the contract expires, the insurer can adjust the rate based on a stated formula or on the yield it is earning on its general account. As a measure of protection against declining interest rates, fixed annuity contracts typically include a minimum rate guarantee.
Fixed Index Annuities
A form of fixed annuity that earns interest due to changes in a market index. Rather than using an interest rate as a benchmark, it uses a stock market index to determine growth.
-
Full protection of principal
FIAs are protected from the volatility of the markets. Money is never invested in the stock market. Your credit strategy tracks the stock market, but you do not own assets that can lose value.
-
Can potentially provide better rates than CDs
From 1999 to 2020, many fixed index annuities outperformed the indexes they were correlated with. However, while this happens from time to time, they are not designed to outperform the stock market.
-
An efficient way to plan for future income needs
Once you annuitize with a lifetime payout option or turn on the income rider payouts, you cannot outlive that income stream.

How annuities help you retire
Annuities can help ensure a retirement strategy and income that lasts as long as you do, which is likely to be a very long time.
-
A Certain Level Of Guarantee
You know what your rate of return will be for a certain period of time with fixed annuities. For seniors looking for a predictable income stream, that may be a better alternative than putting money into equities.
-
Predictable Income For Life
Income riders may be an effective vehicle for lasting financial security. When paired with the right annuity, an income rider can provide a steady income stream for the rest of your life.
-
Tax-Deferred Growth
In general, during the accumulation phase of an annuity contract, your earnings grow tax-deferred. You pay taxes only when you start taking withdrawals from the annuity.
-
Death Benefits For Heirs
The owner can designate a beneficiary to inherit the remaining annuity payments after death. After an annuitant dies, insurance companies distribute any remaining payments to beneficiaries.